On this page
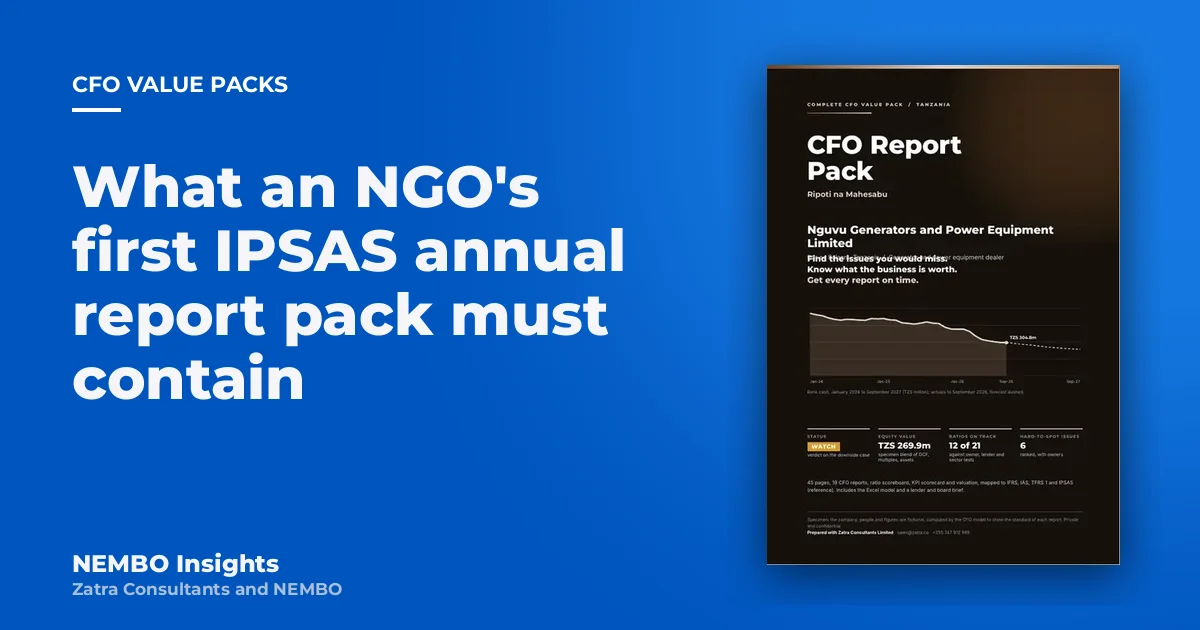
What must an NGO's first IPSAS annual report pack contain in Tanzania?
NBAA Technical Pronouncement No. 3 of 2020 requires NGOs to use IPSAS for periods beginning on or after 1 July 2021 [1]. The pack holds IPSAS 1's statements: financial position, performance, changes in net assets, cash flows, budget comparison and notes [3]. Grant revenue follows IPSAS 47 from 1 January 2026, with unmet obligations held as a liability [4].
An NGO that reported on receipts and payments now sends a donor its first IPSAS annual report. Grant income is lower than the cash received, and a liability for unspent grants appears on the statement of financial position. A finance lead who has not explained that split before the pack goes out receives the query after it.
NBAA Technical Pronouncement No. 3 of 2020 sets the framework. This note sets out what the first pack contains, how grant revenue is split between income and liability on the IPSAS 47 method with exact figures, and what a donor traces line by line.
Which framework applies to an NGO's annual report?
IPSAS applies. Technical Pronouncement No. 3 of 2020, approved at the 182nd NBAA Governing Board meeting on 22 June 2020, requires all NGOs and associations to use IPSASs for general purpose financial statements, effective for reporting periods beginning on or after 1 July 2021, with earlier application allowed and encouraged 1. The text as read states no transition provisions and does not address first-time adoption of accrual IPSAS 1.
What does the first IPSAS annual report pack contain?
IPSAS 1 sets the complete set of financial statements, and TFRS 1 adds the narrative report. TFRS 1 applies to all entities except those applying the micro-entity standard, so an NGO prepares both 23.
| Component | What it shows | What a donor checks |
|---|---|---|
| Statement of financial position | Assets, liabilities, net assets 3 | Unspent grants carried as a liability |
| Statement of financial performance | Revenue and expenses for the period 3 | Grant revenue against expenditure on the programme |
| Statement of changes in net assets | Movement in net assets 3 | Restricted balances brought forward |
| Cash flow statement | Cash in and out 3 | Cash held against the unspent liability |
| Budget comparison | Approved budget against actual, where the budget is public 3 | Variance on the funded lines |
| Notes and policies | Accounting policies and explanatory notes 3 | Revenue policy and grant disclosures |
| Report by those charged with governance | Budget performance, treasury policies, statement of responsibility 2 | Who signed and on what basis |
Comparative information is disclosed for the previous period, so the first pack carries the prior year beside the current year 3. The IPSAS 1 text read is the December 2006 version with amendments to 15 January 2011, and the current text is confirmed with the IPSASB.
How is grant income recognised under IPSAS 47?
Revenue follows the obligations attached to the inflow. IPSAS 47, issued in May 2023, takes effect for periods beginning on or after 1 January 2026 and replaces IPSAS 9, IPSAS 11 and IPSAS 23 45. It has two models, split by whether a binding arrangement exists 45.
- With a binding arrangement, revenue is recognised at the amount allocated to a compliance obligation when, or as, the entity satisfies it 4.
- Without a binding arrangement, revenue is recognised when, or as, the entity satisfies enforceable obligations tied to the inflow, and immediately if there are none 4.
- A capital transfer, an inflow that requires the entity to acquire or construct a non-financial asset it will control, takes the binding arrangement model 4.
For earlier periods under IPSAS 23, the United Nations' IPSAS finance manual treats a donor stipulation as a condition only if it carries both a performance obligation and an enforceable return obligation, and recognises a liability for the conditions 6. The version in force for a given NGO period is confirmed with NBAA.
Source: worked example computed on the IPSAS 47 method described by the IPSASB [4].
Note: illustrative figures on an IPSAS basis with TFRS 1 for the governance report. The version of the revenue standard in force is confirmed with NBAA. Nothing here is an offer or a guarantee of any donor's view.
How does a donor read the pack?
A donor reads the liability line against its own agreement. In the example, the 360 carried forward should equal what the agreements still require the NGO to spend or return, and the cash flow statement should show cash at least that large. Revenue of 790 is read against programme expenditure, and the budget comparison shows whether the funded lines were delivered.
What to do now
- Fix the framework Confirm with the NBAA pronouncement and the NGO's auditor that IPSAS applies to the period.
- List every agreement Record each grant with its amount, period, obligations and return clause.
- Classify Mark each as binding arrangement or not, and each obligation as met, partly met or open.
- Measure Compute revenue and liability grant by grant, as in the example.
- Reconcile cash Show cash held against the liability at the reporting date.
What the NEMBO desk prepares
Zatra Consultants Limited authors and checks the figures, and NEMBO designs and delivers. The Client shares the ledger or trial balance, the grant agreements and the debt schedules. The CFO pack returns with IPSAS with TFRS 1 named as the basis, a verdict, ratios and an action list, a Lender and Board Brief, and an Excel working file with live formulas tied to the ledger 7. Fees are quoted in writing, and the written quote states the date for the scope agreed.
The NGO's auditor and accountant sign the statements. The pack is an illustrative management estimate, not an audit, an assurance report or a valuation, and it decides no donor's view.
An IPSAS pack a donor can trace
The desk prepares the CFO pack on IPSAS with TFRS 1, with ratios, a verdict and an Excel working file tied to the ledger.
Open the CFO deskSources and status
Accurate as at 17 October 2026. Every figure below was read at the source named, on the date shown.
- 1Technical Pronouncement No. 3 of 2020National Board of Accountants and Auditors, Approved 22 June 2020. Accessed 17 October 2026.
- 2Tanzania Financial Reporting Standard No. 1: The Report by Those Charged with GovernanceNational Board of Accountants and Auditors, Approved 22 June 2020. Accessed 17 October 2026.
- 3IPSAS 1 Presentation of Financial Statements (December 2006 text, amendments to 15 January 2011)International Federation of Accountants, IPSASB, December 2006. Accessed 17 October 2026.
- 4IPSAS 47, Revenue: At a GlanceIPSASB, May 2023. Accessed 17 October 2026.
- 5IPSASB issues package of revenue and transfer expense related pronouncementsIPSASB, May 2023. Accessed 17 October 2026.
- 6IPSAS Finance Manual, Chapter 3: Revenue from Non-Exchange TransactionsUnited Nations, undated. Accessed 17 October 2026.
- 7CFO Value Pack: financial reports for Tanzanian businessesNEMBO, undated. Accessed 17 October 2026.
Figures to confirm before you act
- The IPSAS version and revenue standard in force for the NGO's reporting period, with NBAA.
- Whether an NGO moving from receipts and payments reporting has transition relief for its first pack, with NBAA and the NGO's auditor.
- The return clause, obligations and period of each grant, with the donor's agreement.
- The current text of IPSAS 1, including the budget comparison requirement, with the IPSASB.
- For an NGO registered in Zanzibar, the framework and filing position, with Zanzibar's own registry and the NBAA.
This article is general information based on official sources available at the date of publication. It is not legal, tax, valuation or financial advice. Laws and notices change. Verify with the issuing authority or consult Zatra Consultants Limited before acting.
Frequently asked questions
Are all NGOs in Tanzania required to use IPSAS?
Technical Pronouncement No. 3 of 2020 requires all NGOs and associations to use IPSASs for general purpose financial statements for reporting periods beginning on or after 1 July 2021. The text as read sets no size exception, and earlier application is allowed and encouraged.
Why is grant income lower than the cash received?
Cash received for a grant with enforceable obligations is revenue only as the obligations are satisfied. The part not yet satisfied is a liability. In the worked example, 1,150 received gives revenue of 790 and a liability of 360.
Is an unconditional grant revenue on receipt?
Where there is no binding arrangement and no enforceable obligation attached to the inflow, IPSAS 47 recognises revenue immediately. A donor may still restrict the use of funds, and the NGO discloses the restriction. The accountant reads each agreement before applying that treatment.
What changed on 1 January 2026?
IPSAS 47 Revenue takes effect for periods beginning on or after 1 January 2026, with earlier application permitted. It replaces IPSAS 9, IPSAS 11 and IPSAS 23. Which version applies to an NGO period is confirmed with NBAA.
Does TFRS 1 apply to an NGO?
TFRS 1 applies to all entities except those that apply the micro-entity standard, so an NGO prepares the report by those charged with governance beside its IPSAS statements. The report covers budget performance, treasury policies and the statement of responsibility.
What does a donor look at first?
A donor traces the unspent-grant liability to its own agreement, then checks that cash held covers it and that expenditure matches the funded lines. A pack that shows these three lines together answers the first query before it is raised.
Does the pack replace the NGO's auditor?
No. The auditor gives the opinion and the accountant signs the statements. The NEMBO pack is an illustrative management estimate prepared on the basis the accountant confirms, and it is not an audit, an assurance report or a valuation.